The Weekly Compass 19/10/26
 John Mullane
19.10.2026
The Weekly Compass:19/10/2026
CIO, John Mullane, shares the latest Market News and Views and gives insights for the week ahead: French budget and Q3 earnings in focus
The Week That Was
Global equities declined 1.9% in euro terms last week, led lower by the US and Emerging markets as investors digested a mixed start to the third-quarter earnings season, whilst renewed concerns about AI valuations also weighed on sentiment.
European equities benefited from the resultant rotation trade, climbing 2.1% on the week. Global bonds rallied 0.7% in euro terms, led by long-dated bonds, which advanced as expectations for a Federal Reserve rate hike this month declined despite a hotter-than-expected inflation print. Global commodities were little changed despite Brent climbing back to $109 a barrel, its highest level since May.
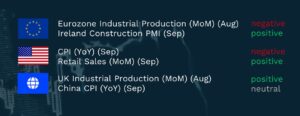
Summary Economic Releases
The Week Ahead
Asia-Pacific markets moved higher this morning as investors responded positively to a raft of economic data from China. Third-quarter GDP growth accelerated modestly on a QoQ basis, while retail sales also improved, reflecting signs that stimulus measures were helping to stabilise the economy and keep it on track to achieve its annual growth target. Brent remained at $107 per barrel, close to its May highs, as markets continued to price in the risk of further supply disruptions despite global oil shipments returning close to pre-war levels.
Corporate updates are likely to be the key driver of market sentiment this week as Q3 earnings season kicks into full gear. In the US, for Meta, investors will be focused on the pace of consumer adoption of Muse alongside the Q4 guide, which should reinforce the strong fundamentals in the core advertising business. For Tesla, the focus will be on evidence of margin recovery, Cyber-cab deployment and any signal about a timeline for a merger with SpaceX, which also report this week. Closer to home, Kerry Group is expected to produce c. 4% organic revenue growth, with Americas and APMEA regions stronger than Europe, where flat growth is expected. Consensus estimates for Barclays point to 6% net revenue growth driven by fees and commission growth of c. 8%, whilst the LSE Group is expected to report a solid 7% revenue growth, with gross profit growth of 8%.
The economic calendar is light of tier-one data this week, but nonetheless there are a number of likely market-moving releases. S&P Global PMI data is likely to indicate a slight moderation in the pace of growth for the month of October on the back of some softness in the services sector. The German ZEW survey may indicate that sentiment towards Europe’s largest economy improved in October and follows a recent upward revision of GDP forecasts. In the UK, a CPI read for September of close to 3.4% YoY will highlight the acuteness of cost-of-living pressures ahead of next week’s Autumn Statement and boost the case for a November BOE hike. Finally, the French budget will face its first test as politicians vote on revenue measures against a backdrop of social unrest, which will likely keep upward pressure on OAT spreads.
This week’s economic data, corporate earnings releases and the French political developments will be closely watched by investors. While the backdrop remains supportive, companies’ ability to meet elevated earnings expectations and the outcome of the French budget vote could have an important bearing on market sentiment. As highlighted in our Q4 Outlook, released this week, maintaining a diversified and actively managed portfolio will be critical to navigating the evolving market environment and capitalising on emerging opportunities.
Written by John Mullane, CIO, Cantor Fitzgerald Ireland
This is an extract from the Weekly Markets Report by Cantor Fitzgerald Ireland. For more detail on individual securities, or to discuss how we can support your investment needs, please get in touch.