The Weekly Compass 09/11/26
 John Mullane
09.11.2026
The Weekly Compass: 09/11/2026
CIO, John Mullane, shares the latest Market News and Views and gives insights for the week ahead: US inflation and tech sentiment in focus in the week ahead.
The Week That Was
Global equities declined 2.5% in euro terms last week as the Democratic sweep of the midterms gave way to a sharp sell-off, particularly in the semiconductor sector. Concerns over a potential curtailment of data centre buildouts pushed the Nasdaq into correction territory and also weighed on tech-heavy emerging markets, which fell 4.0%.
European equities bucked the trend, edging up 0.3%, led by Travel & Leisure names, as expectations of a near-term escalation in US-Iran tensions eased. This also contributed to Brent Crude falling almost 14% to $98 per barrel. The weakness pushed global commodities down 4.4%; however, gold rallied on safe-haven buying. Global bonds also advanced by 0.6% on safe-haven demand and falling inflation expectations.
Summary Economic Releases
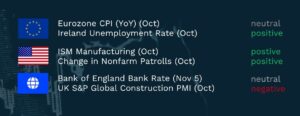
The Week Ahead
Asia-Pacific markets staged a recovery this morning following last week’s losses, as Taiwan adopted measures to boost investor confidence and concerns around AI regulation eased. Brent fell to $97 per barrel after President Trump noted that he is unlikely to renew attacks on Iran if talks show progress, while gold edged marginally higher as the PBOC disclosed that its October purchase rate was the largest in three years.
Financial markets face a busy week on both the earnings and macro fronts in the week ahead. US inflation will be the main focal point from a macro perspective, with a slight moderation in core CPI to 0.2% MoM expected for October, primarily due to easing consumer electronics inflation. Despite these expectations, still-elevated producer price inflation, combined with last week’s strong employment data, leaves a Fed rate hike in December all but assured. Investors will also pay close attention to 10-year and 30-year bond auctions to assess the impact of the Democratic sweep in Congress on demand. Tier-one data from Europe is limited. However, UK Q3 GDP data should point to continued strength in the third quarter, with growth of 0.7% YoY, which is likely to keep the BoE in hiking mode until at least February 2027.
Corporate earnings season is moving into its latter innings. However, a number of market-moving releases remain, particularly in Europe. For Kingspan, today’s results, reiteration of FY26 guidance and projected FY27 guidance were robust. Infineon’s FY26 results will likely focus on PSS growth into FY27, with AI revenue expected to be at least €2.5bn, while Aviva will give its Q3 trading update and Dole is due to report Q3 earnings. Overall, whilst sentiment around reporting season has been weak, reflecting a number of high-profile index weights missing estimates, it has been a strong quarter for global earnings, particularly in the US, where growth is running at over 30% for the quarter.
Overall, with markets continuing to digest the outcome of the US midterm elections, this week’s inflation data will be important in shaping interest-rate expectations. Encouragingly, US equities found support at key technical levels last week, while favourable seasonal patterns, more attractive valuations and resilient corporate earnings provide grounds for a recovery in sentiment. However, further volatility cannot be ruled out, highlighting the importance of portfolio diversifiers such as high-quality fixed income, where starting yields remain attractive.
Written by John Mullane, CIO, Cantor Fitzgerald Ireland
This is an extract from the Weekly Markets Report by Cantor Fitzgerald Ireland. For more detail on individual securities, or to discuss how we can support your investment needs, please get in touch.