The Weekly Compass 05/10/26
 John Mullane
05.10.2026
The Weekly Compass: 05/10/2026
CIO, John Mullane, shares the latest Market News and Views and gives insights for the week ahead: Irish Budget and central bank minutes in focus in week ahead.
The Week That Was
Global equities edged lower last week, although a stronger US dollar ensured euro-based investors were largely insulated from the weakness. US equities declined 0.25%, with Tesla gaining almost 5% on Friday after third-quarter deliveries exceeded expectations. European equities fell 1.1%, while Emerging Markets also moved lower.
Bond markets remained volatile, with concerns around France’s fiscal outlook pushing the 10-year spread over Germany to its widest since 2012, while US 10-year yields reached multi-decade highs before weaker payrolls reduced expectations for further Fed tightening. Global bonds ultimately finished marginally lower, as did commodities, on expectations that the G7 would release some strategic diesel reserves, which eased concerns regarding tightness in global energy markets.
Summary Economic Releases
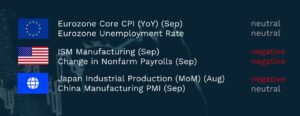
The Week Ahead
Asia-Pacific markets also moved higher this morning on falling Fed rate-hike expectations, in what is a quiet period in the region as China celebrates Golden Week. Brent oil weakened modestly on confirmation that crude exports from the Middle East rose above pre-war levels in late September. The euro weakened against its main currency pairs as French budget negotiations brought its challenging fiscal situation into view.
Financial markets face a quieter, but still important, week for economic data, with investors focused on whether signs of softer US employment are beginning to feed through to the broader economy. September ISM Services is expected to show growth moderating, while employment remains resilient. Minutes from both the Federal Reserve and European Central Bank meetings will be scrutinised on expectations that further hikes could occur this year. In Japan, continued strength in underlying wage growth should keep the Bank of Japan (BoJ) on track for another increase in interest rates in December. Domestically, attention will centre on the Irish Budget, which will provide detail on the Government’s proposed Personal Investment Account, whilst investors will also be watching for confirmation that the deemed disposal tax rate is to be reduced to 35%.
On the corporate side, earnings remain relatively light this week, with PepsiCo and Tesco set to provide an update on consumer demand on both sides of the Atlantic. Shell’s trading update will offer an early indication of third-quarter energy sector performance, while TSMC’s September sales should provide another important gauge of AI-driven semiconductor demand. More broadly, the Q3 earnings season begins in earnest next week, with earnings expectations having been revised higher across both the US and Europe in recent months.
Overall, this week’s data should help establish whether the sharp slowdown in US job creation is consistent with a gradual cooling rather than a broader deterioration in activity. Resilient services activity would support the former, while Japanese wage strength should keep the BOJ on a tightening path, supporting the yen and further reducing intervention risk. More broadly, with the global risk-free rate remaining elevated, delivering on earnings expectations in Q3, rather than multiple expansion, will be key for further equity market gains from here.
Written by John Mullane, CIO, Cantor Fitzgerald Ireland
This is an extract from the Weekly Markets Report by Cantor Fitzgerald Ireland. For more detail on individual securities, or to discuss how we can support your investment needs, please get in touch.