The Weekly Compass 02/11/26
 John Mullane
02.11.2026
The Weekly Compass: 02/11/2026
CIO, John Mullane, shares the latest Market News and Views and gives insights for the week ahead: Earnings & US midterms the key focus in the week ahead.
The Week That Was
Global equities closed broadly flat in euro terms last week despite a sharp sell-off in US tech. The weakness was driven by concerns about the scale of the AI investment alongside mixed earnings guidance, with Intel among the hardest hit, declining 24% and contributing to the Nasdaq falling into correction territory.
The tech weakness also weighed on Emerging Markets, which fell by 0.4%, whilst European equities climbed 1.2%, buoyed by a strong performance in sectors such as Healthcare. Global bonds gained 0.5% in euro terms, providing some protection against equity market volatility. Commodities declined 1.3%, reflecting softer precious-metal prices.
Summary Economic Releases
The Week Ahead
Asia-Pacific markets were mixed overnight as signs of a de-escalation in US-Iran rhetoric brightened sentiment following Friday’s sharp sell-off. Reports suggest US President Trump favours giving diplomacy with Iran more time, pushing Brent down to $109 per barrel. The PBOC met with banks and securities firms to discuss support for capital markets, while Chinese industrial activity contracted in October, highlighting the need for further stimulus.
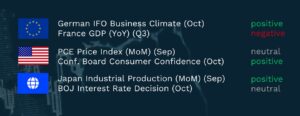
Financial markets face a catalyst-rich calendar on the earnings and macro front. A step-up in Eurozone inflation to 4.0% for October is likely to grab the headlines and strengthen the case for an ECB rate hike in December, despite the limited impact on core. Data from the US should indicate that industrial activity remained strong in October, with investors likely to be focused on the prices-paid component to get a sense of underlying pricing pressure. Non-farm payrolls should point to a step up in US job creation in October; however, it’s set to remain below long-run averages as corporates delay hiring in the face of rising input costs. The US midterms will bring volatility, with a potential Democrat sweep having significant implications for fiscal policy and regulation.
On the corporate side, earnings season is well under way, with this week’s slate having a strong domestic flavour. This morning Ryanair released stable results, while AIB, Flutter, Glanbia, Diageo and Greencoat Renewables are all set to report. Last week’s UK budget is likely to offer support for the construction sector and, as a consequence, a tailwind for Grafton Group, which we see as a solid alternative to DCC. AIB is expected to show a similar picture to Bank of Ireland and PTSB, which already reported solid numbers, and Flutter is expected to have a weak quarter with continued investment in its prediction business. Apple will release the first set of numbers under John Ternus, where focus will be on memory costs, Apple Intelligence adoption and iPhone Duo demand. Overall, US earnings season has been broadly positive, with 82% of companies exceeding expectations, although the magnitude of surprises has been below historical averages, whilst in Europe over 70% of the region’s market cap has reported, with the beat rate running at over 25%.
Overall, while the US midterms may trigger short-term volatility, they could also help clear uncertainty and pave the way for a year-end equity rally, consistent with historical precedent. However, the scale of any further US-Iran escalation will be critical, particularly if higher energy prices reignite inflationary pressures and weigh on both equities and bonds. Against this backdrop, we favour a balanced approach, with attractive bond yields offering a stronger starting point for parts of the fixed income market, while sustainable earnings growth remains key to supporting equity valuations.
Written by John Mullane, CIO, Cantor Fitzgerald Ireland
This is an extract from the Weekly Markets Report by Cantor Fitzgerald Ireland. For more detail on individual securities, or to discuss how we can support your investment needs, please get in touch.