The Weekly Compass 27/10/26
 John Mullane
27.10.2026
The Weekly Compass: 27/10/2026
CIO, John Mullane, shares the latest Market News and Views and gives insights for the week ahead: Tech earnings and central bank rate decisions the key focus for markets this week.
The Week That Was
Global equities declined 0.6% in euro terms last week as investors digested a mixed start to Q3 earnings season, jitters around AI valuations and ongoing tensions in the Middle East. US equities were largely unchanged, but tech stocks experienced bouts of volatility with Meta down over 9% on the week as investors questioned the scale of its AI investment.
Tech volatility also weighed on emerging markets, down 2.4% whilst European equities fell by a more modest 1.4% supported by defensive sectors such as Healthcare and Consumer Staples. Global bonds advanced 0.6%, led by longer-dated bonds as yields eased amid slightly softer macro conditions. Finally, commodities were largely unchanged however Brent crude prices strengthened to $117 on renewed expectations of a near-term escalation between the US/Israel and Iran.
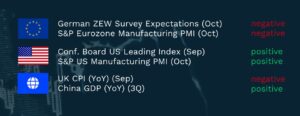
Summary Economic Releases
The Week Ahead
Asia-Pacific markets followed their US counterparts higher overnight, with the prospect of Anthropic’s IPO next month providing a tailwind for technology stocks. Meanwhile, despite exports from the Persian Gulf recovering in line with year-to-date averages, Brent crude remains elevated at $116 per barrel as investors await the outcome of the Israeli elections, which could prove pivotal in determining whether regional tensions escalate or de-escalate near term.
Corporate earnings are likely to be the key driver of market sentiment this week, with 36% of S&P 500 companies reporting. Updates from Alphabet, Microsoft and Amazon will provide an important test of the AI trade, with investors particularly focused on whether strong cloud growth can support elevated market expectations. For Alphabet, cloud performance and any commentary on the rollout of its agentic AI offering will be closely watched, while for Microsoft and Amazon the strength of Azure and AWS respectively will be key. Across all three hyperscalers, investors will be focused on capital expenditure plans and the expected return on those investments. Elsewhere, Smurfit Westrock, GSK, TotalEnergies, Shell, CRH and Bank of Ireland are due to report, whilst a potential High Court decision on the proposed PTSB takeover will attract attention.
The economic calendar is also busy this week and will have a significant bearing on market price action. The Federal Reserve, ECB and Bank of Japan are all expected to leave rates unchanged when they meet this week as a rise in bond yields has served to tighten financial conditions. It is likely however all three will strike a hawkish tone with another 25bps expected by year-end. US 3rd quarter GDP is expected to accelerate to 3.2% annualised on the back of strong AI investment and a resilient consumer, whilst Eurozone growth should see more modest 1.0% growth, however, this is still above trend. Finally, Labour is aiming to deliver a ‘do no harm’ budget this week, with the government’s fiscal credibility on the line amid limited fiscal buffers and high borrowing costs.
Overall, with higher bond yields offering increasing competition for capital, corporate earnings delivery, particularly in tech, will be critical to sustaining the equity market rally. The Israeli election and next week’s US mid-terms will likely inject volatility into markets near term, reinforcing the case for a balanced and diversified investment approach in the weeks ahead.
Written by John Mullane, CIO, Cantor Fitzgerald Ireland
This is an extract from the Weekly Markets Report by Cantor Fitzgerald Ireland. For more detail on individual securities, or to discuss how we can support your investment needs, please get in touch.