The Weekly Compass 12/10/26
 John Mullane
12.10.2026
The Weekly Compass:12/10/2026
CIO, John Mullane, shares the latest Market News and Views and gives insights for the week ahead: Q3 earnings season the key focus.
The Week That Was
Global equities advanced 1.3% in euro terms last week, supported by resilient US equities and a stronger dollar, despite continued volatility in sovereign bond markets. The S&P 500 gained 1.8%, European equities were broadly unchanged whilst emerging markets rose 0.6%. From a sector perspective, consumer staples and energy led sector performance whilst industrials were under pressure.
Global bonds gained 0.4% in euro terms, although returns were negative in local currencies, as longer-dated yields remained elevated amid inflation and fiscal concerns. French sovereign bonds remained under pressure, with spreads over German bonds widening amid political uncertainty and concerns surrounding the country’s budget. Commodities advanced 2.4%, supported by ongoing geopolitical tensions and elevated energy prices.
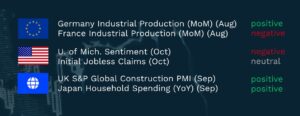
Summary Economic Releases
The Week Ahead
Asia-Pac markets moved marginally higher this morning following reports that Russia and Ukraine had agreed to a ceasefire covering energy infrastructure. The move saw oil prices edge lower, while diesel futures fell 3.0% after Russia agreed to increase exports as part of an agreement brokered with President Trump. China has also agreed to restrict hybrid vehicle sales to the EU as part of a broader trade agreement, which should be a modest positive for European autos this morning.
Financial markets face another important week, with US inflation data, French political developments and the start of the third-quarter earnings season all likely to set the tone for asset prices. US core CPI is expected to strengthen modestly to 2.5% YoY in September, with the release particularly important given recent volatility in Treasury yields. September retail sales and the Fed’s Beige Book will provide insight into the resilience of the US economy. In Europe, market-moving macro data points are light, with auctions of 5 to 7-year debt by France providing another test of investor appetite amid elevated yields and widening spreads.
On the corporate side, third-quarter earnings season gets underway with JPMorgan, Bank of America and Goldman Sachs among the first companies to report. While the higher-for-longer interest rate environment should support net interest income in the near term, investors will focus on its impact on loan demand, credit quality and broader capital markets activity. Investors will also be focused on whether strong trading revenues can offset subdued dealmaking activity. More broadly, US corporate earnings are expected to deliver a third consecutive quarter of growth of more than 25%, and with equity markets trading near all-time highs, meeting those expectations will represent an important test of investor sentiment.
Overall, events this week will provide a litmus test for financial markets. With equity indices trading close to all-time highs, delivery on corporate earnings expectations will be crucial in determining whether markets can extend their recent gains. While the economic backdrop remains supportive, we continue to believe balanced and diversified portfolio positioning across asset classes, sectors and regions remains appropriate, particularly given ongoing volatility in the fixed income markets.
Written by John Mullane, CIO, Cantor Fitzgerald Ireland
This is an extract from the Weekly Markets Report by Cantor Fitzgerald Ireland. For more detail on individual securities, or to discuss how we can support your investment needs, please get in touch.