The Weekly Compass 28/09/26
 John Mullane
28.09.2026
The Weekly Compass: 28/09/2026
CIO, John Mullane, shares the latest Market News and Views and gives insights for the week ahead: Eurozone inflation and US Jobs data in focus this week.
The Week That Was
Global equities moved higher last week, supported by signs of easing US-Iran tensions and renewed enthusiasm for tech. The S&P 500 gained 1.2%, with Meta among the standout performers, rising 14% as investors reacted positively to its Muse AI agent. European equities advanced a modest 0.5%, while Emerging Markets rose 1.3%.
Technology was the best-performing sector, whereas Financials and Energy lagged, with the latter weighed down by softer oil prices, which also pressured broader commodity markets. In fixed income, longer-dated bond yields remained under pressure, but the strength of the dollar largely offset this impact for euro-based investors, leaving global bond returns broadly flat.
Summary Economic Releases
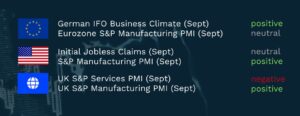
The Week Ahead
Asia-Pacific markets were marginally higher overnight, led by gains in Hong Kong following further signs of easing US-China trade tensions. The two countries agreed to pursue more favourable tariff terms on approximately $30bn of goods deemed non-sensitive, supporting investor sentiment. Japanese equities were weaker, while the yen strengthened as markets increased bets on an October rate hike by the Bank of Japan. Brent crude rose 2.5% to $107 per barrel after Iranian officials indicated they would not soften their demands following the US rejection of a proposed ceasefire agreement, although negotiations are expected to continue.
Financial markets face another data-heavy week, with key releases from both the US and Europe likely to influence expectations for growth and interest rates. In the US, the ISM Manufacturing survey is expected to show an acceleration in activity, reinforcing the view that economic momentum remains resilient. Nonetheless, a moderation in payroll growth, while still above the pace required to stabilise unemployment, alongside unchanged core PCE inflation, could reduce expectations of an October Fed rate hike.
In Europe, headline inflation is expected to rise to its highest level since the outbreak of the US-Iran conflict earlier this month, although limited pass-through to core CPI may leave the ECB on course to conclude its tightening cycle in December.
On the corporate front, strong memory pricing evident in Micron’s results could provide a catalyst for the stock and the broader sector. For Nike, expectations heading into the quarter remain subdued, with investors hoping resilience in the US market can offset ongoing weakness internationally, while also looking for tangible evidence that management is delivering on its turnaround strategy. Elsewhere, Accenture’s results should offer a read-through on enterprise technology spending and TotalEnergies CMD will provide an update on its medium-term outlook.
Overall, this week’s data should reinforce the picture of a global economy continuing to show resilience, despite some moderation in the US labour market. Firmer European inflation and resilient US activity support our expectation for relatively shallow hiking cycles in both the US and Europe, particularly as renewed US-Iran engagement reduces substantial upside risks to energy prices. However, as long as the risk-free rate remains elevated, earnings growth rather than further multiple expansion will increasingly be needed to drive equity returns.
Written by John Mullane, CIO, Cantor Fitzgerald Ireland
This is an extract from the Weekly Markets Report by Cantor Fitzgerald Ireland. For more detail on individual securities, or to discuss how we can support your investment needs, please get in touch.