The Weekly Compass 21/09/26
 John Mullane
21.09.2026
The Weekly Compass: 21/09/2026
CIO, John Mullane, shares the latest Market News and Views and gives insights for the week ahead: Trump-Xi Summit the key focus.
The Week That Was
Global equities moved marginally lower last week. However, dollar strength cushioned the impact for euro-based investors. The S&P 500 ended largely flat whilst European equities fell 0.5%, with the defensive Healthcare sector the outperformer in a risk-off week. Global commodities rose 1.3% in euro terms, buoyed in part by a rally in precious metals such as gold. In addition, Global bonds rose 0.4% in euro terms with long-end yields stabilising as a more hawkish global central bank posture gave markets confidence that the inflation threat was being taken seriously.
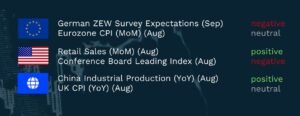
Summary Economic Releases
The Week Ahead
Asian markets were largely higher this morning, led by tech, as the US and China held constructive talks on AI. The positive tone has raised expectations that a Trump-Xi summit later this week could see their trade truce extended. Brent fell for the 4th consecutive day as President Trump indicated he may meet his Iranian counterpart at the UN General Assembly this week. Elsewhere, the Euro moved lower as both the German Far-Left and Far-Right made gains in state elections at the weekend, thereby putting the future of Friedrich Merz’s chancellorship in the balance.
Financial markets face another important week, with September flash PMI data from the US and Eurozone expected to show economic activity expanding, although the surveys are unlikely to fully capture the recent commodities rebound. Energy costs will also be in focus as the French Government seeks to balance deficit reduction with ongoing cost-of-living pressures in its budget framing. European bond markets will be closely monitoring the budget proposals due this month as fiscal concerns have already contributed to credit rating downgrades and spread widening. Elsewhere, the German IFO should indicate business confidence improved in September whilst Irish retail sales should provide colour on how cost-of-living pressures are affecting consumers ahead of October’s budget.
On the corporate side, reporting is again relatively light as markets cycle through the fallow season before the commencement of Q3 earnings season in October. Nonetheless, Q3 results from US retailer Costco should provide a good temperature check on the strength of the US consumer, with investors also particularly focused on the membership growth, comparable sales and margins for the group. McDonald’s Investor Day will also be in focus as it’s set to unveil its new medium-term growth targets, whilst closer to home, investors will be looking for further evidence of Origin Enterprises’ ongoing transition from a low-margin distributor to a higher-margin, tech-led agronomy services business in its full-year results.
Overall, this week’s PMI data will help indicate whether economic activity remains resilient against an increasingly volatile geopolitical backdrop, whilst investors will also digest the impact of German state elections and remain alert to French fiscal developments that could put upward pressure on European yields and downward pressure on the Euro. Whilst we remain constructive on risk assets, elevated valuations, higher long-term yields and renewed fiscal uncertainty support a balanced and diversified approach across asset classes, sectors and regions.
Written by John Mullane, CIO, Cantor Fitzgerald Ireland
This is an extract from the Weekly Markets Report by Cantor Fitzgerald Ireland. For more detail on individual securities, or to discuss how we can support your investment needs, please get in touch.