The Weekly Compass 14/09/26
 John Mullane
14.09.2026
The Weekly Compass: 14/09/2026
CIO, John Mullane, shares the latest Market News and Views and gives insights for the week ahead: Central Bank updates the main focus for markets.
The Week That Was
Global equities moved three-quarters of a percent lower in euro terms last week on renewed bond market volatility and rising tensions in the Middle East. European equities declined 1.7% whilst the S&P 500 fell 0.8%, with AI bellwether Oracle falling, despite better-than-expected earnings and guidance.
From a sector perspective, Healthcare and Materials were among the biggest laggards whilst Energy was the stand-out performer. Global commodities rose 1.9% in euro terms, supported by a rally in oil, which culminated in Brent closing the week at $105 a barrel. The resultant rise in inflation expectations saw global bonds decline by 0.5% in euro terms, principally driven by a sell-off in the long end whilst the short end was broadly flat on the week.
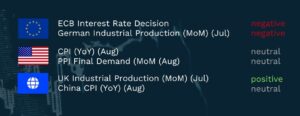
Summary Economic Releases
The Week Ahead
Asian markets were mixed this morning as tech weakness and geopolitical volatility weighs on sentiment. Brent oil pushed close to $108 as Saudi Arabia was forced to close its East-West pipeline (4-5% of global supply) following a drone attack.
Elsewhere, a call to slow the pace of AI development by industry players weighed on the sector even as Anthropic reportedly posted a second profitable quarter ahead of its expected October IPO, which represents the next major test of the AI trade, a float Nvidia may anchor with a $10bn investment.
Financial markets face another important week, with policy decisions from the Federal Reserve, BOE and BOJ likely to set the tone for global bond and currency markets. Firmer inflation, resilient employment data and a likely rebound in retail sales increase the prospect for a hike when the Fed meets on Wednesday.
Investors will focus as much on Chair Kevin Warsh’s guidance and updated dot-plot for indications of how much further policy may need to tighten. The Bank of England, (BOE) is set to stay on hold, whilst the Bank of Japan (BOJ) is expected to tighten on Friday, with its guidance particularly important to reinforce recent yen strength. Elsewhere, a raft of Chinese data will be analysed for signs of stabilisation in the domestic economy.
On the corporate side, reporting is relatively light this week with the outlook for the housing sector the key focus. In the UK, Barratt Redrow’s (the home builder) full-year results will offer further insight into UK housing demand, margins and progress on the Redrow integration. Investors will be hoping that strong cost discipline from US homebuilder Lennar can drive an expansion in margins as elevated mortgage rates (US 30-year 6.8%) weigh on demand. Closer to home, Supermarket Income and Greencoat report this week. Greencoat confirmed healthy dividend coverage and that asset recycling/investment plans remain on track, whilst for Supermarket Income, the focus will be on portfolio rental and cost performance, given the recent purchase of 6 assets for c. £100m.
From a CIO perspective, evidence of a more hawkish bias from central banks this week could reassure bond investors by helping to anchor inflation expectations and reduce volatility at the long end. While the macro and earnings backdrop remain supportive for risk assets, the repricing of interest-rate expectations will likely keep downward pressure on multiples in the short run, particularly for growth stocks. Against this backdrop, we believe an increasingly balanced and diversified approach across asset classes, sectors and regions remains appropriate.
Written by John Mullane, CIO, Cantor Fitzgerald Ireland
This is an extract from the Weekly Markets Report by Cantor Fitzgerald Ireland. For more detail on individual securities, or to discuss how we can support your investment needs, please get in touch.